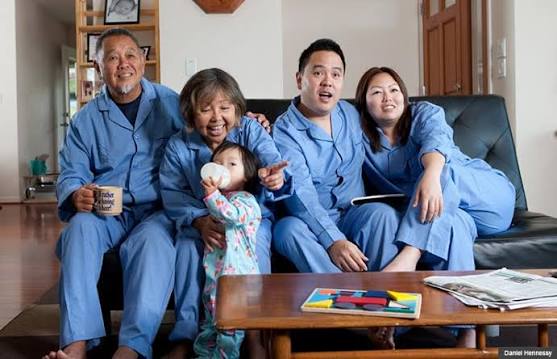
A multigenerational home may run on several incomes, unpaid help and arrangements that nobody has written down. Before discussing life insurance, identify what each adult contributes and what the others would need if that contribution stopped. The address is shared, but the financial consequences of a death may be quite different for each person living there.
Consider a hypothetical Canadian household with two working adults, their children and a retired parent. The parent contributes to groceries and collects the children from school. One working adult pays the mortgage; the other covers most recurring household bills. Describing this simply as a family of five misses the relationships that keep the home functioning.
A shared kitchen can contain several budgets
Start with what actually happens during an ordinary month. An adult may make one bank transfer that appears to cover everything, while another pays several smaller bills directly. A contribution that looks modest on a statement may also include driving, meal preparation or supervision. Write these down in everyday language before trying to turn them into insurance amounts.
It helps to separate personal spending from spending that supports someone else. A parent’s own hobby expenses do not have the same role as their contribution to property costs. Likewise, a working adult’s income is not entirely available to the household. Looking at actual contributions makes the discussion more specific than comparing everyone’s salary or pension income.
Shared living can also conceal expenses outside the home. Someone may support a relative elsewhere, pay costs associated with a previous household or contribute to an adult child’s education. These commitments deserve a place in that person’s planning even when they do not appear in the home’s shared account. No resident needs to disclose every private detail to the whole family.
A useful conversation therefore has both shared and private parts. The household can discuss the costs of keeping the home running. Each adult can then discuss personal obligations and policy details with an appropriate adviser. Agreement about groceries does not require everyone to become involved in another person’s medical history or insurance application.
Trace the contribution that would disappear
Next, consider one person’s absence at a time. If the adult paying the mortgage died, the immediate concern might be housing payments. If the retired parent died, the working adults might face a different problem: finding childcare compatible with their schedules. These are illustrative possibilities, not predictions about what a particular family would need or what insurance would pay.
The Financial Consumer Agency of Canada describes life insurance as financial support after death, including help for dependants and income replacement. Applying that basic purpose to a shared home means identifying who would experience the shortfall, rather than assuming the oldest or highest-earning resident is the only person whose contribution matters.
For a broad introduction to the category, Specialty Life Insurance’s family coverage information can sit alongside the household’s own notes. A general explanation provides vocabulary for the discussion. It cannot establish the right amount for several adults with different debts, resources and intentions, or confirm that a particular applicant will qualify.
Avoid counting every possible adjustment as an unavoidable expense. One adult might change working hours; a relative might offer limited help; the family might prefer to buy a service. Record these as alternatives with practical limits. A plan becomes misleading if it assumes unpaid help that the proposed helper has never agreed to provide.
Housing intentions need room for disagreement
Keeping the current home may be important to one person and less important to another. A surviving adult might want time to decide rather than an indefinite commitment to the property. Before attaching an insurance amount to the house, discuss the desired outcome: remain permanently, stay through a school transition or have flexibility to relocate.
Do not turn that conversation into a conclusion about ownership. Paying part of a mortgage, living in a home and appearing on property documents are separate facts. Questions about legal interests, estate arrangements or responsibility for borrowing belong with qualified professionals reviewing the actual documents. Family expectations alone cannot settle those matters.
It is also possible for two adults to include the same shared expense in separate calculations. That does not automatically mean the protection is wrong, but the overlap should be intentional. An adviser can help distinguish two separate death scenarios from a calculation that simply adds the same housing cost twice within one scenario.
Time changes the picture. A grandchild may need less supervision later; an adult may retire; the older parent may choose different accommodation. These possibilities do not need exact dates to be useful. They help explain why the household should revisit its assumptions instead of treating today’s arrangement as a permanent family structure.
Turn the household picture into an individual enquiry
Each adult can now describe their own purpose more clearly. One enquiry may concern several years of support for children. Another may concern a smaller, longer-lasting obligation. The next discussion can address available policy types, premiums and duration without forcing every resident into the same product or the same coverage amount.
Any proposed policy still needs its own review. Confirm the person insured, policyowner, intended beneficiary, benefit conditions and payment responsibilities. If an arrangement involves property, trusts or several family branches, obtain advice suited to those details. The fact that everyone currently lives together does not remove the need to understand each individual contract.
At the next family discussion, give every adult space to name one contribution they think the others may have missed. It could be money, time or an obligation outside the home. That small exercise can reveal more about the purpose of protection than a quick comparison of incomes, and it leaves room for the household to evolve.